MAIN MENU
Ashneer Grover’s ₹22,000-crore UPI comparison conflates a personal-guarantee insolvency haircut with public payment funding
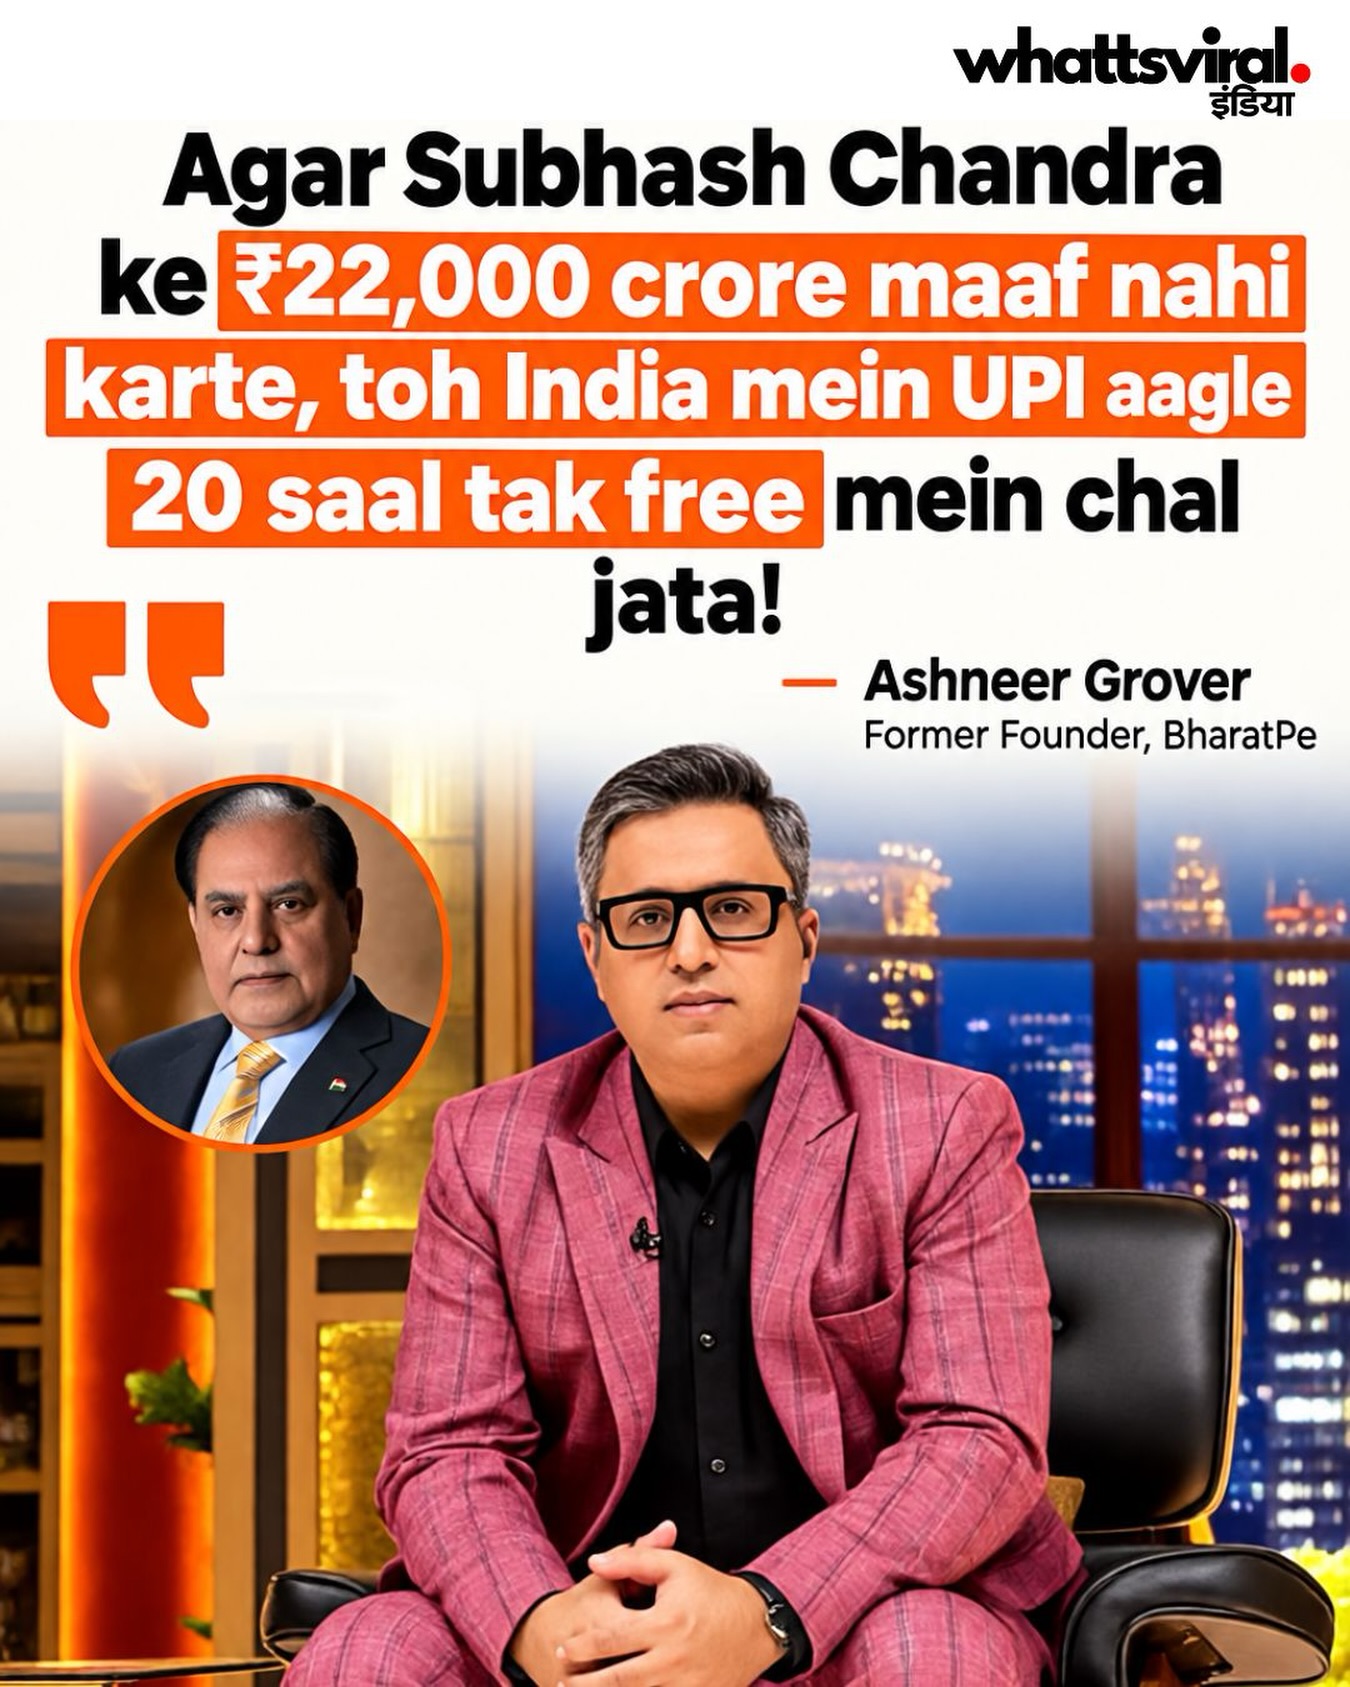
A WhattsViral India graphic attributes to Ashneer Grover the claim that ₹22,000 crore linked to Subhash Chandra could have funded free UPI for 20 years. The comparison is misleading: the ₹22,006.57 crore figure concerns admitted claims in Chandra’s personal-guarantor insolvency process, not a demonstrated pot of government revenue, while UPI funding and MDR are separate policy flows; the record does not establish Grover’s underlying cost calculation.
A viral quotation graphic published by WhattsViral India attributes to former BharatPe co-founder Ashneer Grover the claim that, if Subhash Chandra’s “₹22,000 crore” had not been waived, the money could have kept UPI free for 20 years. The comparison points to two real and current controversies — an unusually low recovery from Chandra under a personal-guarantor insolvency plan and the introduction of merchant charges on some UPI payments — but it joins them in a way the available evidence does not support.
What the ₹22,000-crore figure represents
The National Company Law Tribunal approved a repayment plan in Subhash Chandra’s personal insolvency proceeding involving admitted creditor claims of about ₹22,006.57 crore. The plan provides roughly ₹6.25 crore from Chandra’s personal insolvency estate, an extremely small recovery against the admitted claims. Some lenders opposed the plan and have considered appeals.
But the ₹22,000-crore figure is not established as money personally borrowed by Chandra and then forgiven by the government. Reporting on the proceeding describes the claims as arising from personal guarantees connected to debts of Essel Group and related borrowing entities. Chandra has also disputed the common description of the case as his own ₹22,000-crore borrowing. Creditors may retain recovery rights against principal borrowers and their assets. Calling the entire amount a government “loan waiver” therefore obscures the legal and financial structure of the case.
The UPI comparison also lacks a demonstrated funding link
UPI’s cost model is a separate policy question. For FY 2024–25, the Union government approved a ₹1,500-crore incentive scheme for low-value BHIM-UPI merchant transactions. In September 2026, a new framework introduced a 0.4% merchant discount rate for specified person-to-merchant transactions above ₹2,000, with exemptions and caps; person-to-person transactions and most merchant transactions remain outside the charge. The government says the MDR is distributed within the payment ecosystem rather than collected as a government tax.
Nothing in the evidence reviewed establishes that the ₹22,000 crore in admitted personal-guarantee claims was public revenue available to finance UPI, or that preventing the insolvency haircut would have placed ₹22,000 crore in a government fund. Nor does the ₹1,500-crore incentive scheme represent the full annual operating cost of UPI. Dividing ₹22,000 crore by an assumed annual UPI cost and declaring “20 years free” therefore does not establish a fiscal equivalence.
What the comparison does reveal
The stronger public-interest connection is not a transferable ₹22,000-crore pot of money, but two questions of cost allocation. Chandra’s case raises scrutiny of creditor recovery and the effectiveness of personal guarantees when the guarantor’s recoverable estate is small. The UPI debate asks how the cost of a rapidly expanding payments network should be divided among government, banks, payment companies and merchants while protecting users and small businesses.
Those questions can be compared as matters of financial accountability, but they are governed by different institutions, legal claims and funding flows. The viral formulation is therefore misleading in its fiscal implication: the insolvency haircut cannot, on the evidence reviewed, be treated as ₹22,000 crore of government money that could simply have paid UPI costs for two decades.
Evidence boundary
This record assesses the claim as circulated by WhattsViral India and the documented structure of the Chandra insolvency proceeding and UPI funding framework. It does not establish Ashneer Grover’s underlying source or calculation for the “20 years” estimate, and it does not determine the outcome of any appeal or later creditor recovery against borrowing entities.
